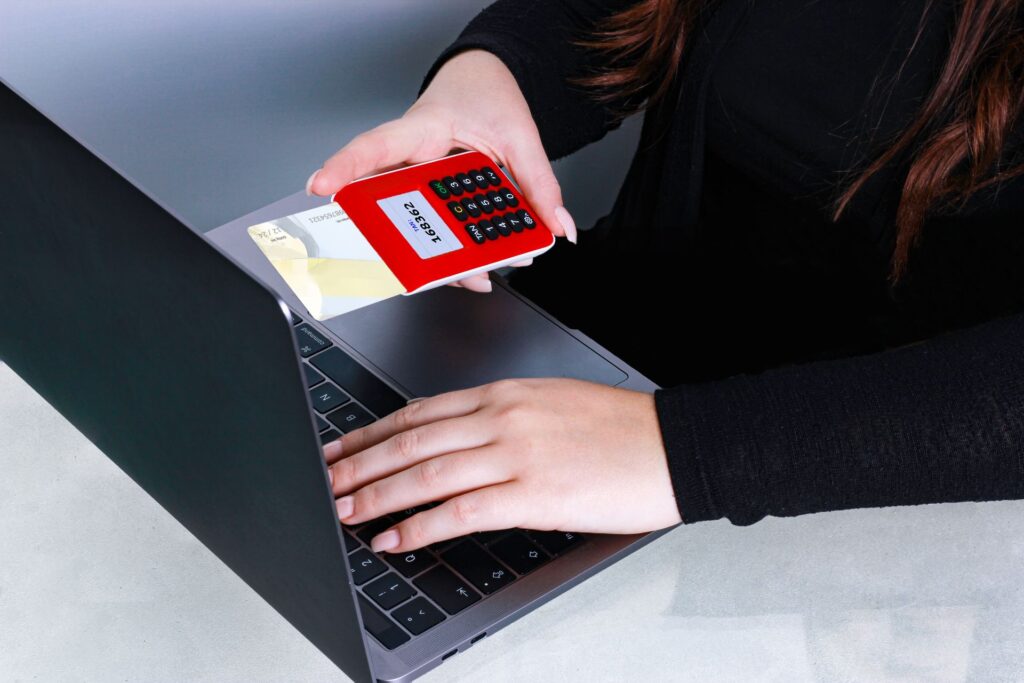
A payment account is only as secure as its quickest login. The good news is that a few deliberate settings can turn everyday transfers into a workflow that is harder to hijack, easier to audit, and far less dependent on memory.
Step 1: Map the accounts that can move money
Start with the apps, bank portals, digital wallets, and marketplaces that can send or receive funds. Remove old payment methods and close accounts that are no longer used. Fewer active routes mean fewer passwords, recovery emails, and notification settings to overlook.
Step 2: Secure the email address behind the account
Email is often the master key to a payment profile because password resets land there first. Use a unique password, enable two-factor authentication, and review recovery addresses and phone numbers.
A locked payment app does little good if an attacker can reset it through an unprotected inbox.
Step 3: Turn on passkeys where they are available
Passkeys replace reusable passwords with credentials tied to a device and its screen lock.
Services using WebAuthn can verify that credential without asking you to type a password that could be captured by a fake login page. Set up a passkey on a primary device, then make sure recovery options are current before relying on it.
Step 4: Add a backup login method
Keep one backup method that doesn’t depend on the same phone. A FIDO2 security key is a strong choice for an account that holds meaningful balances or business funds.
If the service only offers a time-based one-time password, store its backup codes in a secure password manager rather than in a screenshot folder.
Step 5: Verify recipients before the first transfer
Create a short pause before money leaves the account, especially when adding a new recipient. Compare the name, account details, and destination with information obtained through a separate trusted channel.
An online money transfer service should show the recipient name, destination, exchange rate where relevant, fees, and the expected arrival time before a transfer is approved.
Step 6: Use limits as a safety rail
Set transaction, daily, or withdrawal limits if the platform provides them. Low limits can feel restrictive until a device is lost or a login is compromised.
Increase them only for a planned transfer, then reduce them again afterward; this small habit narrows the damage a fraudulent session can cause.
Step 7: Separate payment notifications from marketing noise
Enable alerts for new logins, password changes, new recipients, and completed transfers. Route them to an inbox or notification channel that is not flooded with promotions.
A meaningful alert needs to be visible within minutes, not buried beneath delivery updates and sales emails.
Step 8: Treat transfer requests as potential impersonation
Urgency is a favorite tool in payment scams. A message that appears to come from a colleague, seller, family member, or support team can still be fraudulent.
Don’t use a number or link supplied in that message to verify it. Open the official app yourself or contact the person through a known channel.
Step 9: Protect the device, not just the app
Use a device passcode that is not easily guessed, install operating-system updates, and avoid approving sensitive transfers on shared computers.
Public Wi-Fi isn’t automatically unsafe, but a personal cellular connection or trusted network reduces the chance of landing on a malicious hotspot or lookalike sign-in page.
Step 10: Review the record after money moves
Check the confirmation screen, saved recipient details, and transaction history after each important transfer.
For recurring payments, review permissions and payment methods every few months. This is also the moment to spot an unfamiliar device, a changed contact detail, or a transfer that needs to be reported quickly.
Security doesn’t need to make digital payments cumbersome. A passkey, an independent backup, careful recipient checks, and immediate alerts turn a routine transfer into a controlled action, exactly how money-moving technology should feel.

 There is a specific skill involved in explaining something clearly — one that is completely separate from actually knowing the subject. Dorothy McMorrowinnie has both. They has spent years working with software development updates in a hands-on capacity, and an equal amount of time figuring out how to translate that experience into writing that people with different backgrounds can actually absorb and use.
Dorothy tends to approach complex subjects — Software Development Updates, Latest Tech Innovations, Graphic Design Trends being good examples — by starting with what the reader already knows, then building outward from there rather than dropping them in the deep end. It sounds like a small thing. In practice it makes a significant difference in whether someone finishes the article or abandons it halfway through. They is also good at knowing when to stop — a surprisingly underrated skill. Some writers bury useful information under so many caveats and qualifications that the point disappears. Dorothy knows where the point is and gets there without too many detours.
The practical effect of all this is that people who read Dorothy's work tend to come away actually capable of doing something with it. Not just vaguely informed — actually capable. For a writer working in software development updates, that is probably the best possible outcome, and it's the standard Dorothy holds they's own work to.